Lendersa® database fosters hard money lenders who are lending 100% LTV for Fix N' Flip transactions and other circumstances such as property acquisition and blanket loans. A true 100% LTV financing is different than 100% financing of the purchase price. We shall guide you on presenting your loan request to private investors via hard money lenders in California, Texas, Florida, and all other states to get the best possible 100% loan.
LTV, LTC, and ARV
Property owners wishing to get a real estate loan must be familiar with different kinds of LTV. Buyers looking for loans on Fixer-Uppers should know the definition of LTV, ARV, and LTC.
LTV is an abbreviation of Loan To Value, and it the ratio between the loan amount the property value. For example,
property value $400,000 loan amount $300,000 the LTV is $300,000/$400,000 = 75%.
ARV- ARV is the abbreviation of After Repair Value. The future value of the property after all the repairs/ rehabs are completed. For Fix N' Flip properties, the lenders sometimes base the loan amount on the property's future value.
LTC- LTC is the abbreviation of Loan to Cost and is the ratio between the loan amount to the total cost of the project. For example, property cost $400,000, the rehab cost is $50,000, and the loan amount is $300,000 the LTC will be 66.66% $300,000/($400,000+$50,000) = 66.66%. The formula to calculate the LTC is Loan Amont/(Purchase Price+Rehab Costs) = LTC
Many lenders have a maximum LTC when underwriting construction loans, and hard money loans which require rehab. Conservative lenders will stay under 70% LTC, and more aggressive lenders will lend at 75% and even 80% LTC.
For a single property the maximum loan amount often calculated with this formula: Maximum Loan Amount= (Purchase Price + Rehab Costs)* max LTC
Three kinds of LTVs
Although there is only one definition of LTV, the definition of "Value" can mean three different things hence 3 kinds of LTVs. Value could be:
The purchase price
The property market value (Also known as As-Is Value)
The Property value after repair- ARV (After repair value)
If you buy a distressed property, you might be lucky to pay less than the true property market value. Some lenders will consider a maximum loan amount based on the property market value instead of the purchase price. Here are the formulas for three kinds of LTV:
LTV based on the purchase price: LTV- Purchase = (Loan Amount)/(Purchase Price)
LTV based on market value (As-Is): LTV- Market Value= (Loan Amount)/(Market Value)
LTV of ARV is the loan to value based on future after repair value: LTV-ARV= (Loan Amount)/(After Repair Value)
The property value can be determined by an appraisal or by the lender's internal valuation. Some properties are easy to evaluate, and some properties are very difficult to evaluate. An appraisal opinion of value is only an opinion. The property's actual value could be more or could be less than the value assigned by the appraiser. As a rule of thumb, hard money lenders tend to accept conservative appraisals. When making a decision on the maximum loan amount, the lenders will often use the lesser of the purchase price or the appraisal price
What is 100% LTV
When the loan amount is equal to the property value, the LTV is 100%. In practice, it means that the lender is financing 100% of the property value.
On a purchase transaction, the property value is equal to the purchase price, and if the lender is willing to lend 100% LTV, it means that the lender will finance the entire purchase price.
VA and USDA lenders can sometimes lend up 100% of the purchase price. Hard money lenders will lend 100% of the purchase price but only in these three situations:
The property is a fixer, and the buyer plan to fix it and sell it for a much higher price than the price that he buys it. (See below additional conditions)
The buyer is offering an additional property with lots of equity as additional collateral
The purchase price is much much lower than the actual property value. (This is rare but could happen)
In many cases, all three situations are combined to achieve a 100% LTV loan.
If the borrower has very strong equity in properties that he already owns, the lenders can often lend more than 100% to cover all costs and the rehab money.
Fix and Flip 100% LTV
The most sought for 100% LTV loans are the 100% Fix N' Flip loans. Lendersa® database fosters hard money lenders who are lending 100% LTV for Fix N' Flip loan transactions and other circumstances such as blanket loans. The conditions for lending high LTV loans on Fix and Flip properties are:
After Repair Value (ARV) should be under 75% LTV
The borrower has substantial experience in buying, fixing, and selling fixers
The borrower has good credit
The borrower has some "skin in the game." Skin in the game could be part of all the cash required for the rehab or additional equity in another property.
The loan amount should not exceed the lender's maximum LTC requirements.
When the buyer does not own another property to pledge for security, a lender can still fund 100% of the purchase price, providing the buyer can pay for the repair/ rehab costs. The buyer must deposit all or some of the repair money into a fund-controlled escrow. During the repair period, the lender will inspect the rehab progress and authorize escrow to release funds in certain predetermined repair/construction stages.
100 LTV with blanket loan
To avoid putting money in escrow fund control, the buyer could pledge another property with sufficient equity. It is not uncommon to lend 100% by taking an additional property as collateral. The blanket loan can in the second position on another property.
Analysis of 100% LTV of the purchase price on Fix and Flip Loans
The table shows four scenarios of loan purchase with about 100% LTV of the purchase price. In all the example A, B, C, and D the borrower need to have the cash for the rehab money. For the example, we assume that the ARV for scenarios A and B is $160,000 and the ARV for scenarios C and D is $280,000. The LTC is the maximum LTC (Loan to Cost) allowed by the lenders. Every lender set its own Max LTC and sometimes can have different max LTC for various loan programs.
e
f
g
h
i
j
k
l
m
e Fixer Purchase Price
f Rehab Costs
g Fixer Purchased ARV
h=e+f Total ProjectCost
i Loan to Cost(LTC)
j=h*i Max Loan Amount
k=j/e LTV of Purchase
l=j/g LTV of ARV
m=h-j Cash Needed
A
$100,000
$28,000
$160,000
$128,000
75%
$96,000
96%
60%
$32,000
B
$100,000
$28,000
$160,000
$128,000
80%
$102,400
102%
64%
$25,600
C
$200,000
$50,000
$280,000
$250,000
75%
$187,500
94%
67%
$62,500
D
$200,000
$50,000
$280,000
$250,000
80%
$200,000
100%
71%
$50,000
In Scenario A, the borrower gets only 96% LTV of the purchase price instead of 100% and is required to have $32,000 in cash to rehab the property.
In Scenario B, the borrower gets a loan of 102% LTV of the purchase price but must have $25,600 in cash to rehab the property. The borrower is getting a bigger size loan in "B" because the lender requires only 80% LTC instead of 75% LTC in the scenario "A."
In Scenario C, the lender is willing to lend is only 94% LTV because of the 75% maximum LTC. The borrower will need to have $62,500 in cash to complete the transaction.
In Scenario D the lender's 80% allows the borrower to get 100% LTV of the purchase price. The borrower needs to have $50,000 for the rehab costs.
100% LTV financing for the entire project- True 100% LTV
Question:
Could I get 100% financing that includes the rehab costs? In other words, can I get a loan that requires no money from my pocket?
Yes, but the property must have lots of equity, or you can pledge an additional property that has lots of equity. "Lots of equity" is relative to the lenders' guidelines. The table below shows how combined LTV enables 100% of the purchase and all the rehab costs. The borrower pledges additional property that has $150,000 in equity.
n
o
p
q
r
Additional Property Value
Additional Property Existing Lien
h=p If New Loan 100% LTV of Project
(o+p)/(e+n) Combined As-Is LTV
(o+p)/(g+n) Combined ARV LTV
A
$200,000
$50,000
$128,000
59%
49%
B
$200,000
$50,000
$128,000
59%
49%
C
$200,000
$50,000
$250,000
75%
63%
D
$200,000
$50,000
$250,000
75%
63%
If the lender agrees to lend 100% to cover the purchase and the rehab cost of the purchased property, the combined LTV in scenarios A and B is 59%. The combined As-IS LTV in scenarios C and D is 75%. Scenario C and D are riskier, but the combined ARV LTV might mitigate the risk.
Using an additional property with equity, some lenders will allow the borrower to bigger loan to cover all the rehab cost and other costs associated with buying the property and getting the loan
The general formula to calculate combined market (As-Is ) LTV is
As-Is combined LTV = (Purchase Price+Reab costs+Additional property Loan Amount)/(Purchase price+Market Value of Additional property )
The general formula to calculate ARV LTV is
As-Is combined LTV = (Purchase Price+Rehab costs+Additional property Loan Amount)/(Purchase price+Market Value of Additional property )
Important note: The underwriting of 100% LTV can be done with many different formulas. The above are only examples. Hard money lenders are private investors; they make their own rules, and they change those rules to adapt them to market conditions and availability of funds. The only question a private lender asks himself is: Is it Safe?. If the lender feel safe (and legal safe), he will fund the loan.
How to qualify for blanket loans?
To qualify for a loan using more than one property, the lender must evaluate both properties. Most hard money lenders do not offer blanket loans, and your first step is to locate lenders who provide loans secured by two or more properties. Blanket loans can take a longer time to approve loans, and when fund control and construction are involved, it requires a higher level of sophistication by the lender.
Lendersa® loan request enables you to enter all the factors a lender needs to decide on one page. You can then complete the page request under 10 minutes and forward it to lenders that you already know or use Lendersa® advance matching calculator to send your request only to lenders who offer blanket loans or blanket loans plus constructions.
Lenders who arrange 100% LTV loan
Only a small percentage of hard money lenders arrange loans with high LTV. Most hard money lenders will go only to 65%. Without additional collateral or the buyer putting a substantial amount of money for the repair, no hard money lenders will fund 100% of the purchase price.
Getting lenders to fund 100% is a complicated process
The first step is to find lenders who even consider 100% financing.
You then need to find out the maximum LTC (Loan to Cost) the lender allows
Find out the maximum LTV the lender will consider on the additional property.
It can get complicated because there are many other factors involved in the lender's decision.
Borrower credit, experience, type of property, location, market trend, income, and other factors can swing the loan approval in many directions
If any, the prior relationship between the lender and the borrower can also impact the lending decision.
Lendersa® will get you a list of hard money lenders near you, who arrange 100% LTV loans, but you will be better off to complete a short loan request which will give the potential lenders a full picture of what you need and what you have. Instead of spending hours explaining and completing separate loan applications for every qualified lender, Lendersa® will only distribute your loan request to lenders who could do 100% financing. You could also use the loan request to contact lenders who are not yet members of the Lendersa® network of hard money lenders. Start here to get a 100% LTV loan with the property location.
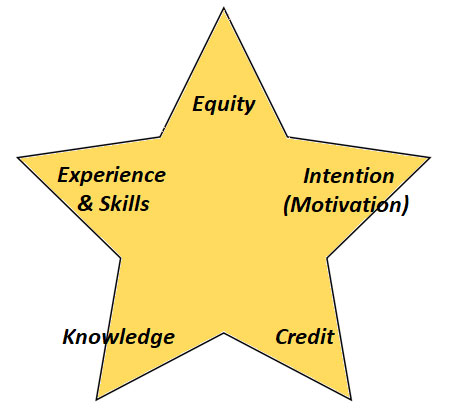
There are 5 ingredients to a successful 100% financing.
Equity
Intention (Motivation)
Experience & Skills
Credit
Knowledge
Equity-You could get 100% financing with equity alone, but you will be getting a lousy loan without the other ingredient. Trying to get 100% financing without equity is close to impossible. Still, you can overcome this hurdle by finding family or friends who have cash or equity in their properties and are willing to partner with you on your project.
Intention (Motivation)-Your firm intention to get the loan done is essential, and it is the glue the binds together the other four ingredients. When you do not have equity use your intention to recruit family and friends to partner with you. It means that you will have to give part of your profit, but it is better than nothing!
Experience & Skills -Lenders like to lend to experienced flippers. If you have successfully fixed and Flip properties in the past, you will enjoy it better rate and terms and higher LTV and LTC. Lenders will look more favorably on the loan if you are in the building/ real estate trade. Licensed contractors, real estate agents, engineers, and developers can get better loans because they pose less risk.
Credit-. Hard money loans are primarily based on equity and not on credit; therefore, you could get the loan regardless of your credit score. However, good credit always helps with rate terms and higher LTV and LTC provided by the lenders
Knowledge- Understanding how the lenders think and knowing what is needed can save you time and aggravation. Lendersa undercut the time it takes to learn about hard money loans in general and 100% financing. Instead of spending hours on seminars and reading books, complete the Lendersa loan request in 10 minutes. The request includes all the data lenders need to decide on your 100% loan request. The loan request will be instantly delivered to only those lenders who have matching loan programs, and only the best lenders will contact you and guide you on how to get the loan approved.