2026 AI Find the Best Bridge Loan lenders for Sidney, Richland County, MT
Bridge loan rates in Sidney, MT begin at 2.53% for first-position loans, with the same rate for second-position loans. Lendersa® offers a comprehensive list of financial institutions and private hard money lenders who can arrange Bridge Loans for residential and commercial properties throughout MT.
Our bridge loan calculator shows the current rates for residential or commercial bridging loans, helping you determine the required income, credit, reserves, and documents for qualification.
In specific scenarios, hard money lenders might fund your bridge loan mortgage quickly, potentially within days, relying solely on the property's equity without needing additional documentation.
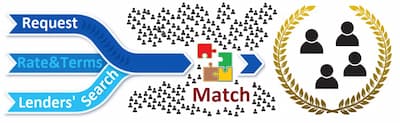
Lendersa® is focused on securing the best Bridge loan options for you promptly and without hassle. Select one of three starting points to connect with matching lenders and bridge loan programs.
The Lendersa® Bridge mortgage calculator allows you to compare lenders and identify the best bridging loans, up to $1,440,000 in first position or starting at $20,103 in second position.
Lendersa® aggregates loan program data from thousands of Bridge loan providers, such as bridge credit unions and civic financial services, and promptly evaluates this data against your specific financial profile and needs.
Understanding Bridge Loans
The term "bridge loan" involves bridge lending, swing loans, or Bridge financing, encompassing several definitions and distinct loan programs tailored to client intentions. Learn how Bridge loans function, or submit your information, and we will instantly match you with the best bridge loan lenders.
To find the precise distance from Bridge lenders to your property, input the property address or location here:
Richland Federal Credit Union is a member-owned credit union that serves Richland and Roosevelt Counties in Montana, as well as other communities in northeast Montana and northwest North Dakota. We offer friendly customer service, competitive interest rates on Agricultural, Consumer and Real Estate loans, and a robust commitment to our community
509 North Merrill Avenue, Suite A, Glendive, MT, 59330
Lends in Montana
The Credit Union is a member-owned financial organization providing the most accessible and competitive financial services to meet the needs of our members, while maintaining long-term stability and growth BN Federal Credit Union's charter of membership includes all employees of: Action For Eastern Montana Albertson Food and Drug and more
Our mission is simple to provide the best service and most competitive rates for you the member.Services Provided: Share Accounts Share Certificates (CD's) Vehicle Loans Recreation Vehicle Loans Personal Loans Payroll Deduction for Savings Deposits Payroll Deduction for Loan Payments
Western Bank of Wolf Point is a locally owned bank that will serve its constituency with integrity & commitment for the well-being & survival of our community. The bank contributes pro-active leadership & human resources to help our community. The bank provides the necessary products & services to accommodate the diverse needs of our customers.
WOLF POINT FEDERAL CREDIT UNION: received it's federal charter in 1963 with charter #15375. The original Board of Directors had seven members, which remain true today. Credit unions are association of people, owned and democratically controlled by their members. Should they cease to be such, they cease to be credit unions