USDA Vs. FHA Pro and Con comparison in Athol, Worcester County, MA
In the year 2026, the USDA loan limit for Athol in the county of Worcester, located within MA, stands at $336,500. In contrast, the FHA loan limit for a single-family home is set at $472,030.
To explore and compare USDA and FHA loan rates today, consider using the Lendersa® USDA loan calculator. This advanced tool helps you evaluate the necessary income, credit scores, reserves, and documents needed for qualification. It also offers a comprehensive view by allowing you to see USDA, FHA, Conforming, and VA loan options side by side, assisting you in choosing the most suitable program for your unique financial situation in Alabama.
Loan Limits and Down Payment Requirements for 2026 in Athol, County of Worcester, MA
Loan Type
Loan Limit
Down Payment
USDA
$336,500
0%
FHA
$472,030
3.5%
Conventional Conforming
$726,200
3%
Options for USDA and FHA Loans in Athol, MA
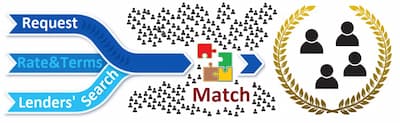
The aim of Lendersa® is to facilitate your acquisition of the best possible USDA or FHA loan swiftly and without hassle. Choose from three different starting points to connect with lenders and find the most suitable USDA loan programs.
A USDA home loan, also known as a USDA rural development loan or USDA mortgage, is a government-backed loan offered by the Department of Agriculture. It is exclusively available in rural areas. Unlike FHA loans, which require at least a 3.5% down payment, USDA loans do not require any down payment at all.
Athol Savings Bank is a mutual savings bank based in Athol, Massachusetts. Our goal is to be the financial foundation in our community; working harder, reaching higher and delivering strength, stability and security to our customers. As we move forward, Athol Savings Bank is committed to being “A Solutions Bank” for our customers.
We were founded in 1930 as a member-owned, not-for-profit credit union with the goal of providing the highest quality banking products at the best possible prices, delivered with professional, one-on-one personal service. In 2015, we were designated as a Community Development Financial Institution by the U.S.
GFA Federal Credit Union is a full service, Member-owned, community financial institution serving Central Massachusetts & Southern New Hampshire, with branch locations in Ashburnham, Gardner, Hubbardston, Keene, Leominster, Peterborough, Rindge, Rutland & Winchendon. Offering Personal, Business, Investment & Insurance solutions to help buy a home.
Greenfield Savings Bank has stayed true to its mission to provide a secure place for local residents to save and to access financial products and resources. Today, we continue that commitment with offices throughout Franklin and Hampshire Counties and through online and mobile banking.
We are a full-service Credit Union, but more importantly, we’re people like you, helping people like you. Yes…we have checking and saving accounts; auto loans and mortgages…you get the gist. But what we pride ourselves most on is helping you through every stage of your life. IC was founded in 1928.
We are a state-chartered 1.7 billion-dollar mutual savings bank with offices in central and western mass. We've gone above and beyond for our customers since 1850. We value respect, courtesy, and excellence in service above all. As a mutual bank, we answer our customers first, not to investors.
Leominster Credit Union is a member-owned, not-for-profit cooperative financial institution. For more than 65 years, we have provided a full range of deposit, lending, and other financial services to North Central Massachusetts residents. Today, we are proud to claim more than 50, 000 members. Leominster Credit Union is headquartered in Leominster,
Leominster Employees Federal Credit Union is a unique non-profit financial institution that is owned and operated for the benefit of its’ membership, the City of Leominster Municipal employees, and their families. The Leominster Employees Federal Credit Union came into being in 1995
The goliath banks of 1888 weren’t interested in providing a high quality banking experience to the hard working middle class of our community. They were only interested in what was in people’s wallets, not what was in their hearts. That’s where we came in. Fidelity Cooperative Bank first opened its doors in 1888.