FHA VS Conventional loan programs in Weston, Fairfield County, Connecticut
As of 2026, the Conventional loan limit in Weston, within the county of Fairfield, CT, is $726,200, whereas the FHA limit for a single-family house is $707,250.
Take advantage of the Lendersa® Conventional loan calculator to compare today's most competitive rates for Conventional, FHA, and USDA loans. Discover the income, credit, reserves, and documents needed to qualify. By using our advanced mortgage calculator, you can evaluate Conforming Conventional loans, USDA, FHA, and VA options side by side to determine which program in CT suits your financial situation best.
Loan Limits and Down Payment Requirements for 2026 in Weston, County of Fairfield, CT
Loan Type
Loan Limit
Down Payment
Conventional Conforming
$726,200
3%
USDA
$556,600
0%
FHA
$707,250
3.5%
This comparison applies to the zip codes: 6883
Conventional and FHA Loan Options in Weston, CT
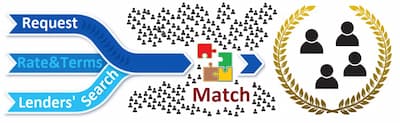
The objective of Lendersa® is to quickly provide you with the best possible loan, whether it's Conventional, USDA, or FHA, without unnecessary hassle. Choose one of three starting points to connect with matching lenders and loan programs.
Provost Capital LLC is a direct private lender making loans to fund the purchase of real estate properties by investors looking to rehab either as a Fix&Flip or a Fix&Rent.
With a deep and committed pool of investor capital, Provost is able to make quick and efficient loan decisions, provide proof of funds letters & fund purchases with A very s
"PFS, Inc. is a family owned and operated mortgage company right here in Fairfield county. We take great pride in working with our fellow neighbors and friends all around Connecticut and New York. Our goal at PFS is to turn all your real estate dreams into reality by offering an array of mortgage products and unparalleled service."
79 South Benson Road, Suite 5, Fairfield, CT, 06824
Lends in Connecticut
BlueCay Capital LLC is a real estate finance firm specializing in directly originating bridge loans collateralized by commercial real estate. We pride ourselves in seeing the value in under-performing or under-valued real estate assets. BlueCay Capital works closely with brokers, borrowers, and investors to ensure secure and timely transactions.
CANNONDALE FINANCIAL LLC has been in business since 1997. We are licensed in New York and Connecticut. We offer mortgage for Residential, Commercial, FHA, VA, USDA, HELOC, Reverse Mortgage and Construction financing There are many factors in looking for the right home loan including your needs, finances and history
Constitution was founded to democratize access to real estate credit opportunities and provide a better more seamless lending experience for borrowers. Our platform leverages our founders' experience investing across the capital structure in real estate, allowing your portfolio to grow with the benefit of our experience.
Edgewood Capital is a private commercial real estate bridge lender focused on providing loans for borrowers acquiring or recapitalizing transitional value-add assets of all property types nationwide. Edgewood works closely with borrowers to provide a quick and customized resolution for their financing needs.
At Prosper First Funding Corp., we feel lucky every day that we are given the ability to help our customers finance a piece of their future. A home purchase is also a very complex undertaking and requires that many elements work cohesively and come together in just the right way.
Connecticut Community Bank, is your locally owned, full service community bank with products to serve the needs of individuals, their families & businesses. Our mission is to be the preeminent provider of financial services to individuals, families, businesses & organizations within our communities. We are dedicated to Customer Service Excellence.
Avant Capital® provides mortgage financing to owners of commercial and multifamily real estate in the $1 to $60+ million range. We focus on properties in major markets nationwide We are experiencing strong demand for our bridge loan product as commercial banks have reduced CRE lending or are unable to meet borrowers’ closing timelines.